
Desktop Virtualization Market Set for 9.8% CAGR as Cloud Migration Accelerates WorldwideMarket ResearchUpdated on Dec 8, 2025 View more like this | Visit NYACK, NY | Contact Global Trends |
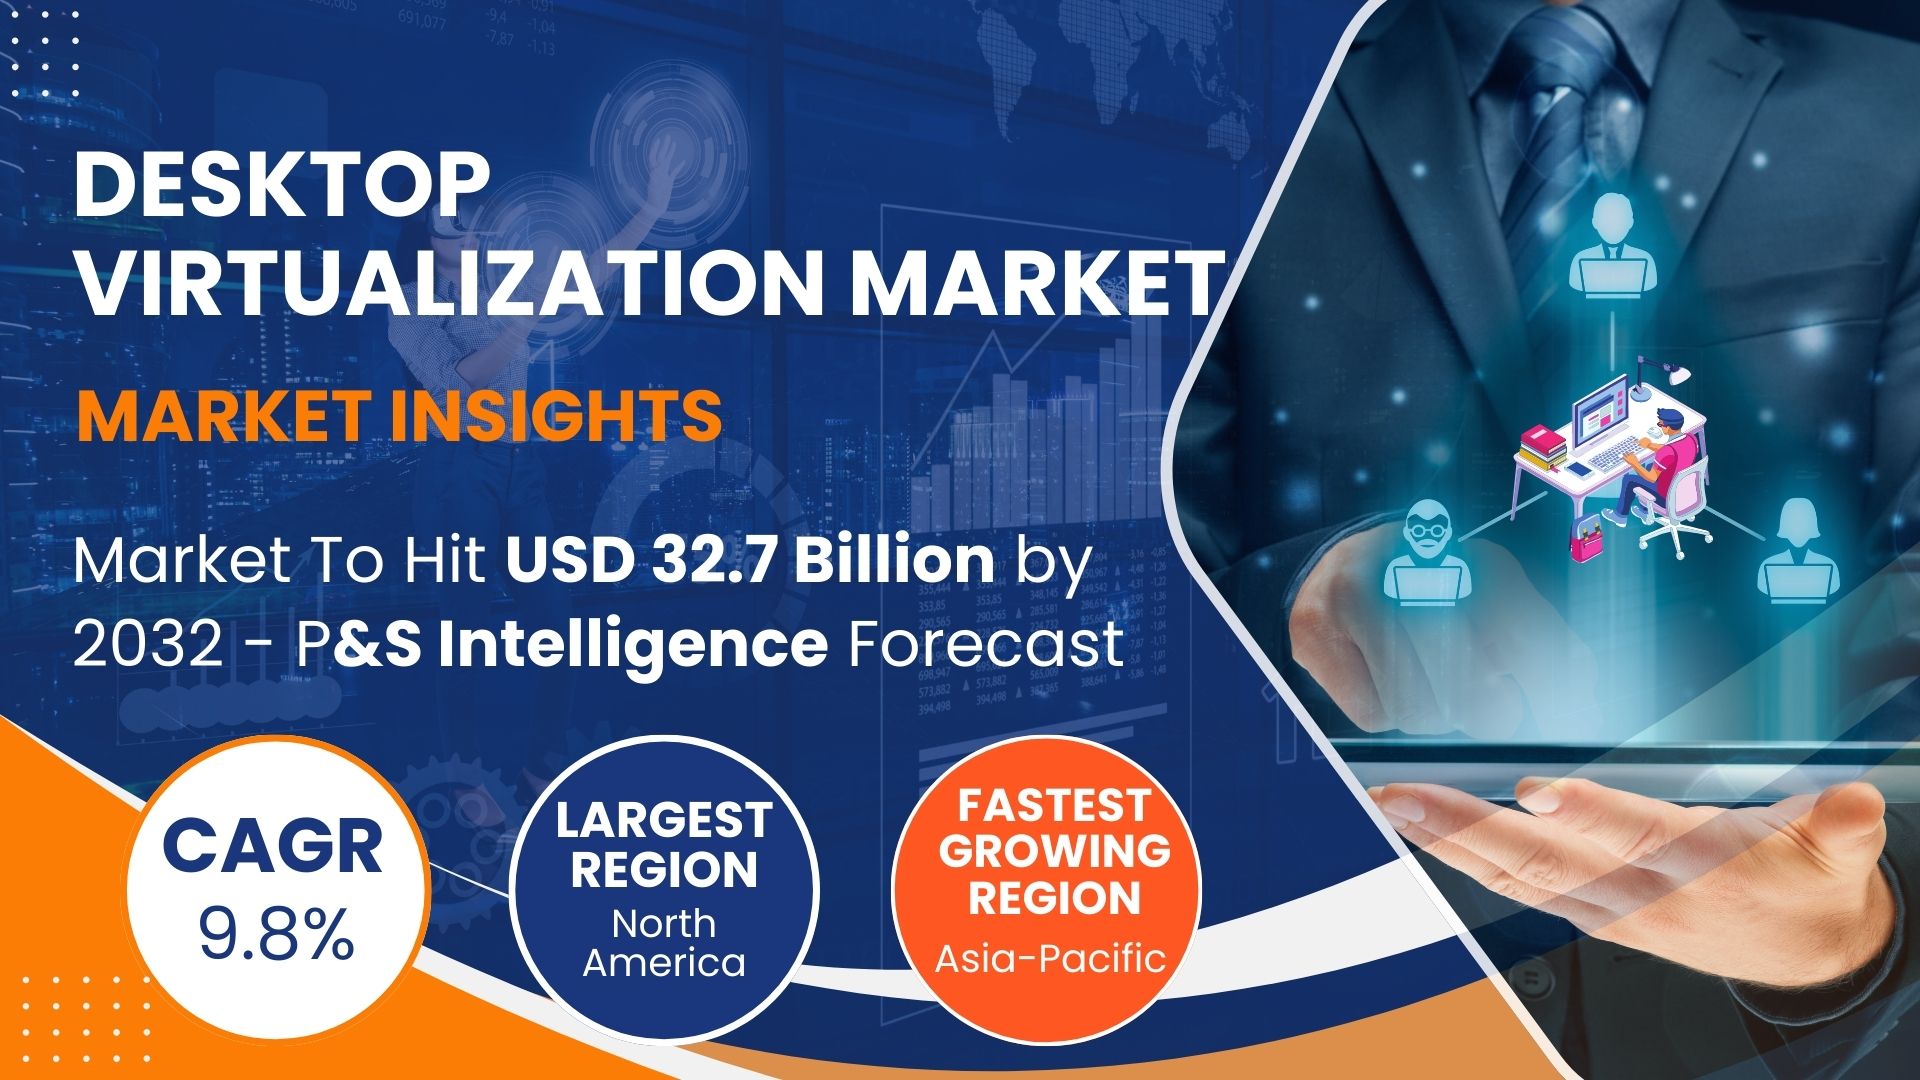
The global desktop virtualization market is experiencing strong momentum, with the revenue standing at USD 15.3 billion in 2024 and projected to reach USD 32.7 billion by 2032, advancing at a 9.8% CAGR during 2025–2032. This rapid growth is rooted in the ability of virtual desktops to simplify administration, lower operational costs, strengthen security, enhance user experience, and support a broad variety of devices—making them an attractive alternative to traditional desktop machines. As organizations strive to modernize their IT environments, virtualization is steadily emerging as a core productivity enabler.
The widespread shift toward hybrid and remote work models is further propelling the market’s expansion. Businesses are rapidly adopting digital workplace solutions that enable employees to operate seamlessly across locations, devices, and time zones. Additionally, following the COVID-19 pandemic, over 40% of organizations adopted cloud-based applications and infrastructure to improve operational efficiency and serve customers more effectively. With enterprises expecting reduced reliance on on-premises systems in the coming years, cloud migration continues to accelerate, giving desktop virtualization a central role in this digital evolution.
Download free report sample at: https://www.psmarketresearch.com/market-analysis/desktop-virtualization-market/report-sample
Key Insights
- Virtual desktop infrastructure (VDI) forms the largest type category, holding a 50% share in 2024, supported by easier in-house deployment, centralized accessibility, and robust security for business-critical databases and applications. Large enterprises prefer VDI due to regulatory compliance needs, better desktop customization, and the ability to centralize all desktops on a single server, which reduces the overall operational cost.
- Desktop as a service (DaaS) is set to grow the fastest at a CAGR of 11.0%, driven by the surge in hybrid work, the demand for secure remote access, and the doubling of the DaaS user base in the past two years. Its flexible management capabilities, rapid workspace creation, and low total cost of ownership make it ideal for businesses seeking to enable remote working and BYOD environments.
- Under the pricing models, subscription-based offerings hold the larger share due to their reliability, convenience, and strong customer–vendor engagement. Meanwhile, pay-as-you-go models will expand at a 10.5% CAGR, appealing particularly to SMEs that seek to pay only for the computing resources they consume.
- Cloud-based virtualization is both the larger and faster-growing server type, expected to progress at 12.0% CAGR. Cloud-based approaches provide scalable access to memory, storage, and processing power via remote data centers. SMEs benefit significantly due to reduced hardware costs and the flexibility to scale IT capabilities as they grow.
- Large enterprises hold 65% of the market share in 2024, driven by heavy use of virtualized systems for centralized data access, enhanced security, disaster recovery, and operational efficiency. Meanwhile, SMEs will grow at 11.0% CAGR, supported by global government initiatives and expanding cloud adoption that helps them reduce costs and integrate advanced digital technologies more easily.
- The IT and telecom vertical dominates with 25% share in 2024, owing to massive IT infrastructure needs and high spending—averaging USD 26,000 per employee—which drives adoption of cloud-based and scalable virtual desktop models. Healthcare is the fastest-growing vertical at 12.0% CAGR, propelled by digital health advancements such as telemedicine, EMRs, remote patient monitoring, and healthcare analytics, as providers seek cost efficiency and better collaboration.
- Regionally, North America leads with 40% share in 2024, supported by advanced IT infrastructure, strong 5G penetration, early cloud adoption, and the growing use of virtual desktops in universities and schools. APAC will grow the fastest, backed by robust economic expansion, significant IT investments, and rising IoT and AI deployments across industries. Investments from major players—such as Oracle’s USD 1.5-billion cloud expansion in Saudi Arabia—are accelerating growth in MEA as well.
- The market remains highly fragmented, featuring a large pool of vendors offering differentiated solutions tailored to varied device environments and compliance needs. Key players include Microsoft, Oracle, IBM, Amazon Web Services, Cisco, Huawei, NetApp, Google, Broadcom, Dell, Cloud Software Group, HPE, and others. Recent developments include Microsoft’s partnership with Lumen Technologies (July 2024), Scale Computing’s VDI promotional launch (April 2024), and Broadcom’s acquisition of VMware (November 2023).
About P&S Intelligence
P&S Intelligence offers custom and syndicated market research and consulting services to clients across the globe. Our team of young and dynamic researchers, guided by mentors with years of experience, create data-rich reports tailored to the needs of MNCs as well as startups and SMEs. We remain in a perennial quest to offer exhaustive insights into every aspect of the market, allowing businesses of all sizes to seize even the smallest of opportunities and tackle even the biggest of challenges.
