
Adipic Acid Market Analysis, Size, and Growth Forecast 2026-2034General BusinessUpdated on Jun 17, 2026 View more like this | Visit BROOKLYN, NY | Contact IMARC Group |
Market Overview:
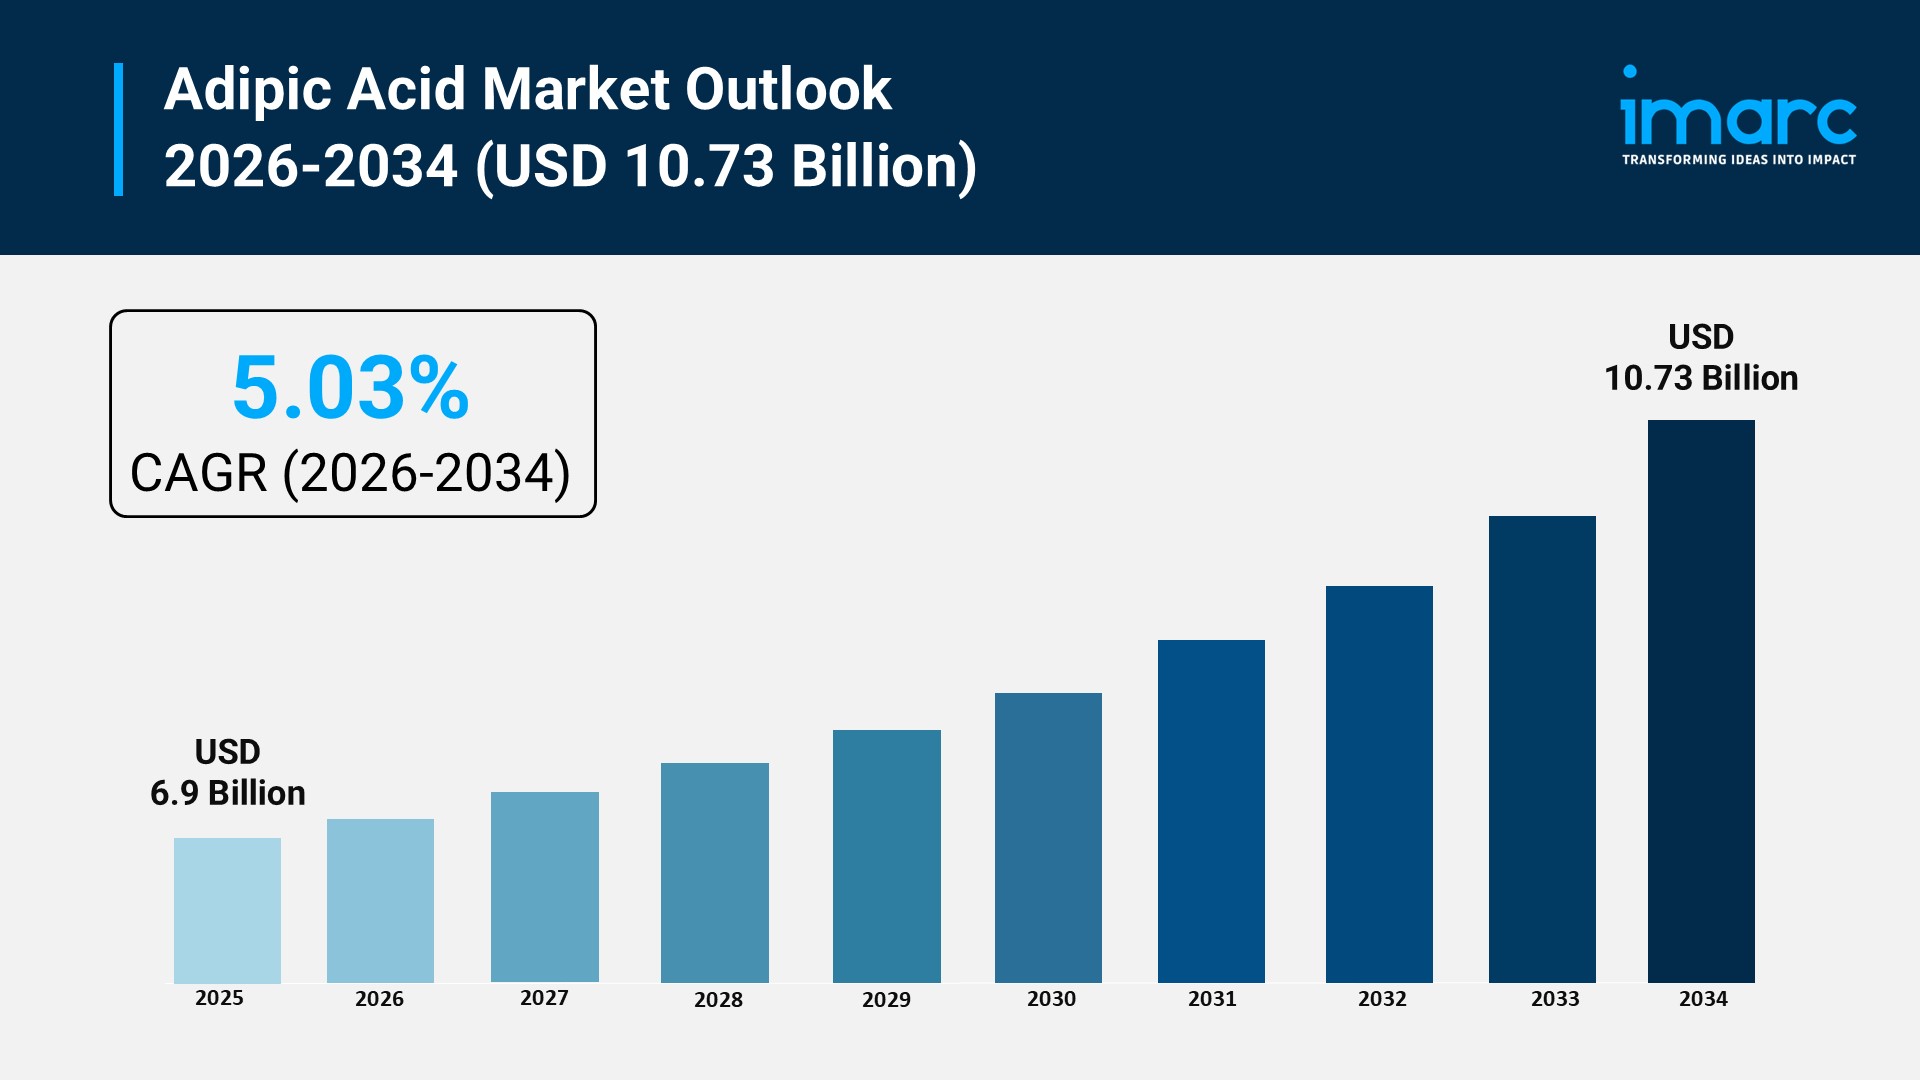
The adipic acid market is experiencing rapid growth, driven by dominant demand for nylon 6,6 production, rapid expansion of automotive lightweighting, and infrastructure development and polyurethane demand. According to IMARC Group's latest research publication, "Adipic Acid Market Size, Share, Trends and Forecast by End Product, Application, End User, and Region, 2026-2034", The global adipic acid market size was valued at USD 6.9 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 10.73 Billion by 2034, exhibiting a CAGR of 5.03% from 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
Download a sample PDF of this report: https://www.imarcgroup.com/adipic-acid-market/requestsample
Our report includes:
- Market Dynamics
- Market Trends and Market Outlook
- Competitive Analysis
- Industry Segmentation
- Strategic Recommendations
Growth Factors in the Adipic Acid Market
- Dominant Demand for Nylon 6,6 Production
The extensive utilization of adipic acid as a foundational chemical intermediate in manufacturing nylon 6,6 polymers serves as a premier driver for industry expansion. Nylon 6,6 is universally favored across the textile, industrial fiber, and engineering plastics sectors due to its exceptional mechanical strength, high thermal resistance, and superior structural durability. Industrial data from IMARC Group indicates that the global adipic acid industry size reached a valuation of USD 6.9 billion, with nylon 6,6 applications capturing over half of the total market volume. This immense share is continuously supported by massive manufacturing activities worldwide. Major chemical enterprises like INVISTA and Domo Chemicals heavily focus on strengthening their structural integration within the nylon value chain. The continuous requirement for high-performance synthetic fibers for consumer apparel, specialized industrial machinery, and heavy-duty conveyor belts sustains a reliable and high-volume procurement framework for adipic acid globally.
- Rapid Expansion of Automotive Lightweighting
Automobile manufacturers are rapidly accelerating the integration of lightweight engineering plastics to enhance fuel economy and satisfy stringent environmental mandates. Nylon 6,6 resin derived from adipic acid serves as an ideal substitute for heavy structural metals in critical under-hood components, including engine covers, air intake manifolds, radiator end tanks, and structural brackets. This shift is highly critical given that global automobile production surpassed 92.5 million units annually, greatly expanding the baseline consumption of high-strength polymer materials. Furthermore, the massive global transition toward electric vehicles amplifies this material shift, as reducing structural weight directly correlates with maximizing battery range. Prominent market participants such as Ascend Performance Materials are actively expanding their regional compounding footprints, exemplified by their strategic plant acquisitions in industrial hubs like Mexico, to meet the specialized high-performance material needs of major automotive original equipment manufacturers.
- Infrastructure Development and Polyurethane Demand
Global investments in modern infrastructure, commercial real estate, and residential construction are fueling substantial consumption of polyurethanes, resins, and specialty coatings, which rely heavily on adipic acid. The chemical functions effectively as a structural crosslinking agent in water-based acrylic emulsions and flexible polyurethane foams used for building insulation, architectural coatings, and durable furniture. National capital allocations are significantly accelerating this industrial demand, illustrated by major public investments such as India’s infrastructure development budget increasing to approximately USD 128.64 billion. This massive influx of capital boosts the need for resilient wiring, industrial coatings, and protective external panels. Leading global chemical suppliers like Lanxess AG and BASF SE are continually adjusting their corporate joint ventures and manufacturing capacities to secure stable supply chains for downstream construction clients who require advanced adipic acid derivatives.
Key Trends in the Adipic Acid Market
- Increasing Adoption of Bio-Based Adipic Acid
Chemical manufacturers are shifting their operational focuses toward green chemistry to counteract the heavy environmental footprint associated with traditional nitric acid oxidation processes. The commercialization of bio-based adipic acid, which utilizes renewable plant biomass or industrial glucose instead of conventional petroleum-derived benzene and cyclohexane feedstocks, represents a significant structural trend. For instance, Toray Industries successfully advanced this movement by commercializing a synthesis pathway that yields 100% bio-based adipic acid from completely inedible biomass resources. This technological breakthrough allows polymer manufacturers to synthesize eco-friendly nylon options without compromising on performance. As consumer preference for sustainable products intensifies, prominent global chemical suppliers are prioritizing bio-synthetic alternatives, effectively transforming supply networks and establishing new production benchmarks that drastically reduce carbon emissions and dependency on finite fossil fuel derivatives across major consumer goods markets.
- Implementation of Advanced Emission Abatement Technologies
Stringent regulatory policies regarding greenhouse gas reduction are compelling chemical producers to implement cutting-edge industrial thermal reduction and carbon capture systems. Traditional synthesis methods generate substantial nitrous oxide emissions, making the sector a primary target for international climate mandates, such as the European Green Deal which targets a 55% reduction in industrial emissions. In response, major market entities are making significant capital investments to clean their legacy facilities. A prime example is Ascend Performance Materials, which operationalized a specialized thermal reduction unit at its primary facility in Florida, successfully destroying 98% of the greenhouse gases generated during adipic acid synthesis. These continuous technological upgrades ensure long-term regulatory compliance while establishing a premium market tier for low-carbon chemical intermediates that appeal to climate-conscious corporate buyers.
- Strategic Consolidation and Value Chain Integration
The global landscape is witnessing intense corporate restructuring as companies execute massive mergers, acquisitions, and joint ventures to secure raw material access and stabilize margins against volatile feedstock costs. Producers are actively integrating their operations from upstream chemical processing directly through to downstream engineering plastics compounding. This trend is clearly highlighted by BASF SE acquiring a 49% stake in Alsachimie to maximize its structural control over polyamide production components, alongside Lanxess finalizing a multi-billion euro joint venture to absorb major engineering materials businesses. These corporate maneuvers allow enterprises to optimize their internal manufacturing efficiency, mitigate regional supply chain bottlenecks for basic feedstocks like cyclohexane, and deliver highly customized polymer solutions directly to automotive, electronics, and packaging end-users under unified corporate umbrellas.
Leading Companies Operating in the Adipic Acid Industry:
- Asahi Kasei Corporation
- Ascend Performance Materials
- BASF SE
- Domo Chemicals
- Invista (Koch Industries)
- Lanxess AG
- Radici Partecipazioni SpA
- Solvay S.A.
- Sumitomo Chemical Co. Ltd.
- Tangshan Zhonghao Chemical Co. Ltd.
- TCI Chemicals (India) Pvt. Ltd.
- Tian Li High & New Tech Co. Ltd.
Adipic Acid Market Report Segmentation:
By End Product:
- Nylon 66 Fibers
- Nylon 66 Engineering Resins
- Polyurethanes
- Adipate Esters
- Others
Nylon 66 Fibers holds 33% market share, used in automotive and industrial textiles, produced from adipic acid and hexamethylenediamine for strength and stability.
By Application:
- Plasticizers
- Unsaturated Polyester Resins
- Wet Paper Resins
- Coatings
- Synthetic Lubricants
- Food Additives
- Others
Plasticizers lead with 26% share, favored for their performance and regulatory compliance in flexible PVC applications across various industries.
By End User:
- Automotive
- Electrical and Electronics
- Textiles
- Food and Beverage
- Personal Care
- Pharmaceuticals
- Others
Automotive dominates with 32% share due to the use of nylon 66 in lightweight vehicle components, driven by the need for fuel efficiency and the rise of electric vehicles.
Regional Insights:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
Asia-Pacific leads with 40% share, supported by strong chemical manufacturing and automotive industries, with China as a major player in production and consumption.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provide a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: [email protected]
Tel No:(D) +91 120 433 0800
United States: +1-201971-6302
